Life insurance
Explore coverage designed to help protect the people who rely on you.
Let’s connect Let’s chat
Protection · Planning · Possibility
Straightforward financial guidance to help Ontario families and business owners protect today and prepare for tomorrow.
No pressure. No confusing jargon. Just clear information about your options.
Personal guidance
Clear education
Long-term relationships
How we can help
Explore coverage designed to help protect the people who rely on you.
Let’s connectPlan for the financial impact of illness, disability, and unexpected health events.
Let’s connectExplore TFSA, RRSP, RESP, and FHSA strategies for retirement and other important goals.
Let’s connectReview protection and planning strategies for business owners and their teams.
Let’s connectRetirement & registered savings
Retirement planning often involves understanding how registered programs can work together. Learning about the available options can help individuals explore strategies suited to their goals and circumstances.
A flexible registered account that can support retirement, emergencies, and other savings goals.
A registered program designed to help Canadians save for retirement while potentially reducing taxable income.
A dedicated way to save for a child’s post-secondary education, with potential access to government education incentives.
A registered program created to help eligible first-time home buyers save toward a qualifying home purchase.
Registered plans have eligibility rules, contribution limits, tax considerations, and withdrawal conditions. Investment products may be offered through a separately registered dealer, where permitted.
Learning Centre
Clear education can make insurance easier to understand. Explore a few insurance fundamentals presented in plain language.
Why coverage exists and the basic differences between temporary and permanent insurance.
How critical illness and disability coverage may help protect your income and plans.
Common factors families consider, including debt, income replacement, and future goals.
General educational information only. Individual needs and product terms vary.
A simpler approach
Insurance, retirement planning, and registered savings programs do not need to feel intimidating. We take the time to understand where you are, explain the available options in plain language, and help you make informed decisions with confidence.
We start with a simple conversation about what matters to you.
We review your goals, priorities, and current financial picture.
You receive clear options and a strategy shaped around your needs.
Insurance 101
Both can provide a tax-free death benefit to the beneficiary, but they are designed for different time horizons and priorities.
Provides coverage for a defined period, such as 10, 20, or 30 years. It often begins with a lower premium and may suit temporary needs such as a mortgage, income replacement, or raising children.
Is designed to remain in force for life when required premiums are paid and the policy conditions are met. It may suit long-term needs such as final expenses, estate goals, or leaving a legacy.
Which one is right? Neither type is automatically better. The appropriate choice depends on your needs, budget, time horizon, and existing coverage. This is general educational information, not a personal recommendation.
Living benefits
Living-benefit coverage is designed to help protect your finances when illness or injury affects your health, income, or ability to work.
May provide a tax-free lump-sum benefit if you are diagnosed with a covered condition and satisfy the policy requirements. The money can generally be used in any way you choose.
May replace part of your employment income when a covered illness or injury prevents you from working. Benefits are normally paid monthly after a waiting period.
Important to understand Coverage is subject to definitions, exclusions, waiting periods, benefit limits, and underwriting. Product availability and tax treatment may vary. This is general educational information, not a personal recommendation.
Planning basics
A useful starting point is to consider what your family or business may need financially if your income, care, or contribution were no longer available.
Review the obligations that may continue and the resources already available.
Think beyond today’s bills to the people and plans that depend on you.
A needs review is not one-and-done Coverage should remain affordable and may need to change after marriage, a new child, a home purchase, a career change, or another major life event. This is general educational information, not a personal recommendation.
TFSA · Registered account
A TFSA is a registered account that can hold savings and investments for short- or long-term goals.
Contributions are not tax-deductible, but qualifying growth and withdrawals are generally tax-free.
The account is flexible, but contribution limits still matter.
TFSA is an account type It is not an investment by itself. Eligible holdings vary, and contribution room should be confirmed using current CRA information. This is general educational information, not tax, legal, or investment advice.
RRSP · Registered account
An RRSP supports retirement saving while allowing eligible contributions to reduce taxable income.
Investments can grow tax-deferred while they remain in the plan.
The value of a deduction depends on individual tax circumstances.
Tax deferral is not tax elimination Suitability depends on current and expected income, contribution room, goals, and other registered accounts. This is general educational information, not tax, legal, or investment advice.
RESP · Registered account
An RESP helps families save for a beneficiary’s qualifying post-secondary education and may provide access to government incentives.
Contributions are not tax-deductible, but savings can grow tax-deferred inside the plan.
Rules affect contributions, beneficiaries, withdrawals, and unused funds.
Plan structure matters Individual, family, and group plans can operate differently. Compare fees, investment options, grant eligibility, and withdrawal rules. This is general educational information, not tax, legal, or investment advice.
FHSA · Registered account
An FHSA helps an eligible first-time home buyer save toward a qualifying home purchase.
Eligible contributions may be tax-deductible, and qualifying home-purchase withdrawals are generally tax-free.
Eligibility, timing, and account-closing rules are important.
Confirm eligibility before contributing FHSA rules can interact with the Home Buyers’ Plan. Current limits and conditions should be verified before opening, contributing, or withdrawing. This is general educational information, not tax, legal, or investment advice.
A complimentary second opinion
You may already have insurance and investments in place. A fresh perspective does not mean starting over—it can help you confirm what is working, understand what you own, and see whether your current approach still reflects the life you are building.
Request a second opinionGain another perspective on whether your current coverage and savings approach still match your priorities.
A review can help uncover outdated information, unanswered questions, or areas worth exploring further.
Clear explanations can help you compare your options without pressure.
There is no obligation to make a change. Sometimes the most valuable outcome is knowing you are on the right track.
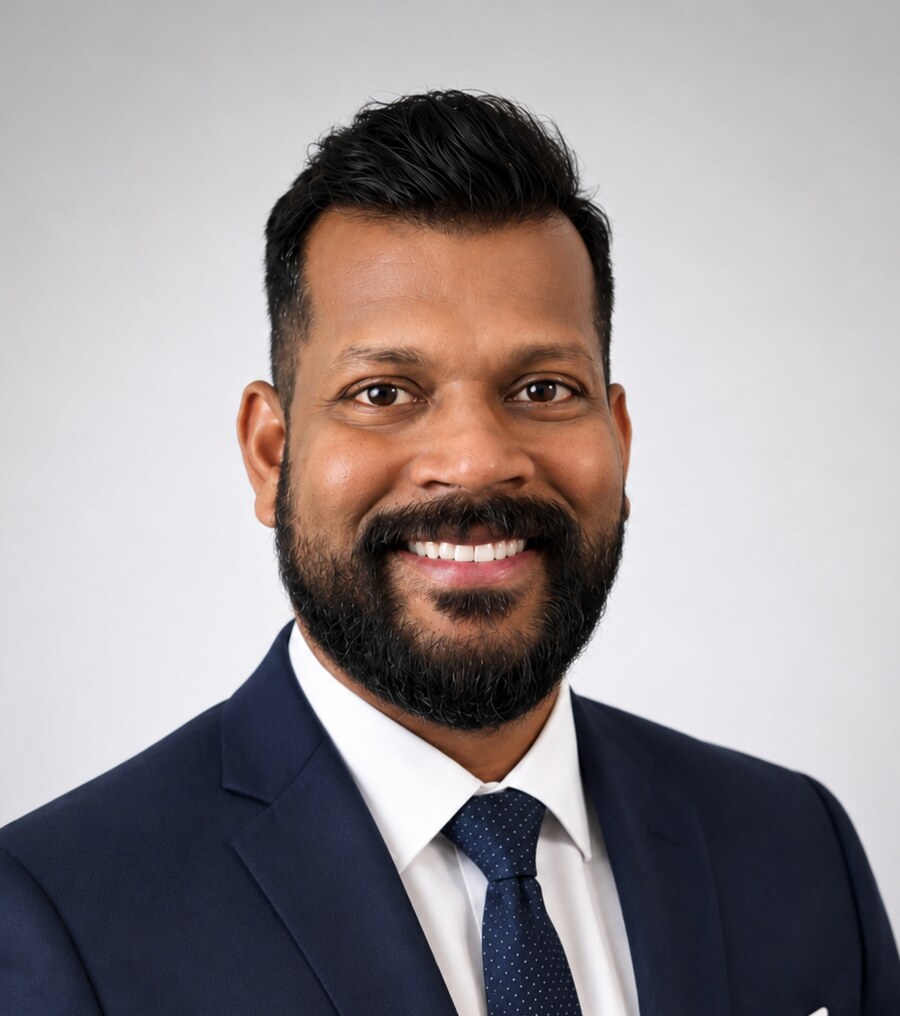
Meet Ruban
I am a family man, a former member of the Canadian Armed Forces Military Police, and someone who genuinely enjoys connecting with people from different backgrounds. My previous career was built on service, integrity, accountability, and remaining calm when people needed support. Those values continue to guide how I support you and your family today.
Family is at the centre of my life and one of the reasons protection and long-term security matter so deeply to me. Like you, I want to provide for the people I love, create meaningful experiences together, and make decisions today that can provide greater confidence about tomorrow.
I also love to travel. Exploring new places and experiencing different cultures has shown me that your journey may be unique, but many of the things that matter most are universal: protecting your family, building stability, creating opportunities for your children, and enjoying the life you have worked hard to build.
My interest in the insurance and financial services industry began with a desire to better understand these decisions for myself and my family. I quickly realized how difficult it can be to find clear, straightforward information when you are trying to understand your options and make important decisions about your future.
Learning about insurance, registered savings programs, investments, and retirement strategies made a meaningful impact on my own life. It gave me a stronger sense of direction and helped me recognize the value of asking better questions before making important decisions.
Through that experience, I also discovered how invaluable it can be to have a broker in your corner—someone who listens to what matters to you, helps you ask the right questions, explains your options clearly, and supports you as your needs change. Important decisions can feel overwhelming when you are navigating these choices alone. Having a knowledgeable and dependable person to turn to can bring clarity, confidence, and peace of mind.
That experience shaped the way I serve you today: education comes first. Before discussing solutions, I believe you deserve to understand the purpose of each option, how it works, what it may cost, and which questions you should be asking. It is about providing clear information, helping you understand your available options, and enabling you to make informed choices for yourself and your family.
My mission is to make insurance and financial education more approachable, understandable, and relevant to your everyday life. By listening carefully and explaining your options in plain language, I aim to help you make informed decisions that reflect your needs, priorities, and future goals.
You do not need to have everything figured out before starting a conversation. Sometimes the most meaningful first step is simply having someone listen, understand what matters to you, and help you see your options more clearly.
Ruban Kumarasamy Licensed Insurance Broker · Ontario
Let’s talk
Share only the basic information needed to coordinate an introductory conversation. Ruban will follow up to confirm the appointment.
Questions are welcome